Worried One Claim Will Wreck Your Renewal? What Actually Moves the Number
title:Worried One Claim Will Wreck Your Renewal? What Actually Moves the Numberauthor:Marguerite Vasquezpublished:2026-11-07section:Personal Financewords:1,213read:5 min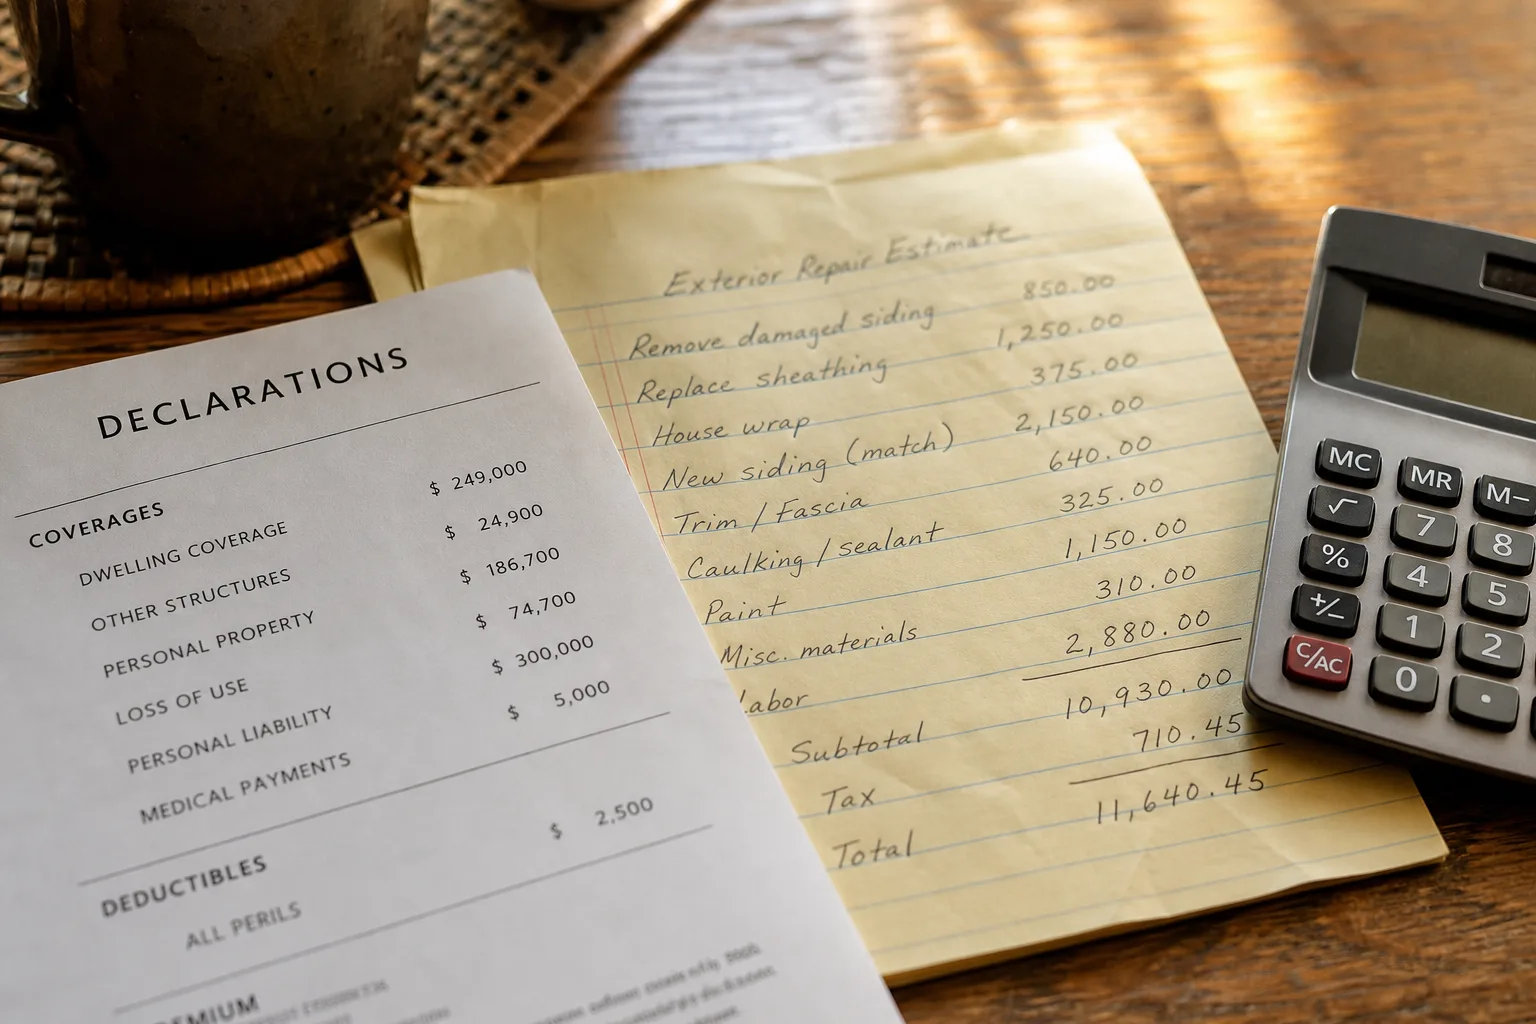
At a large carrier, the renewal consequence of a claim is set by a filed rating rule, not an underwriter's mood. Here is what that rule reads, and how to price the decision before you file.
The advice gets handed around at kitchen tables and on neighborhood message boards as if it were settled: never file a small claim, because the premium increase will cost you more than the check, and eventually they will drop you. It is half right, which is the most expensive kind of right. The half that is wrong sends people into paying out of pocket for losses they have already bought coverage for, and the half that is correct applies to a narrower set of claims than most people assume.
What makes the difference is who is on the other end. A small regional mutual with forty underwriters can and does make judgment calls about a long-standing policyholder. A national carrier writing millions of homeowners policies cannot work that way and does not try. Its renewal decisions run off rules filed in advance with each state's insurance department. That is worse news on some claims and considerably better news on others, and it is knowable before you pick up the phone.
The assumption is about punishment. The mechanism is about prediction
Nobody at a large carrier is annoyed with you. The rating plan is built on one question: does this household's loss history predict future losses? That question produces answers that feel arbitrary from the outside but are consistent inside the model.
A few patterns hold across most large carriers' filed plans:
- Cause of loss matters more than dollar amount. A non-weather water loss, a plumbing failure, an appliance supply line, a slow leak behind a wall, is treated as a strong predictor of another one. Hail damage to a roof on a street where every roof was hit is treated as weather, not as you.
- Catastrophe coding often sits outside the surcharge. When a storm gets a catastrophe designation, losses tagged to it are frequently excluded from the individual loss-history surcharge, because the model already prices that risk through territory.
- Frequency outruns severity. Two claims of modest size in three years typically move a renewal harder than one large claim. The second claim is the one that changes the category you sit in.
- Liability claims are read differently from property claims. A dog bite or an injury on the property touches a different part of the underwriting rules than a burst pipe.
The practical upshot: "will this hurt my renewal" is not one question. It is a question about this specific cause of loss, in this state, under this carrier's filed plan.
The loss-free discount is usually the bigger number
People brace for a surcharge and forget the discount. At most large carriers the visible premium effect of a first claim comes in two parts: a loss-history surcharge, and the loss of a claim-free or loss-free discount that has been quietly compounding on your declarations page for years.
The second part is often larger. It is also the part nobody mentions on the phone, because it is not technically a penalty, it is the removal of a credit you no longer qualify for. If you want a real number, ask for both separately. The phrasing that gets a useful answer is: "If I file a claim for this cause of loss, what is the loss-history surcharge under your filed plan, and what does my claim-free discount drop to?"
The arithmetic, with the assumptions stated
You can price this decision properly, and it takes about ten minutes. The structure is always the same. What you are comparing is the net recovery (claim payment minus deductible) against the added premium over the period the claim stays in the rating, commonly three to five years depending on the carrier and state.
| Input | Where it comes from |
|---|---|
| Estimated repair cost | A written contractor estimate, not a guess |
| Your deductible | Declarations page; check for a separate wind/hail or percentage deductible |
| Net recovery | Repair cost minus deductible, minus any depreciation held back until repairs are done |
| Annual premium increase | Surcharge plus the lost claim-free discount, from your carrier |
| Years in rating | Carrier's filed lookback, typically three to five |
| Total cost of filing | Annual increase multiplied by years in rating |
If net recovery is close to or below the total cost of filing, the claim is probably not worth making. If net recovery is several multiples of it, the hesitation is costing you money. Most claims land clearly on one side or the other, and the ones that genuinely sit near the line are small enough that either choice is survivable.
One correction to the folk wisdom: the lookback runs from the date of loss, and it runs regardless of whether you switch carriers. Moving your policy does not reset the clock.
What the next carrier sees, and your right to read it first
When you shop a renewal, the new carrier pulls a loss history report compiled from industry claim data. It lists losses reported on the property and on you as a named insured, usually going back about seven years, with dates, cause codes, and amounts paid.
That report is a consumer report. The Federal Trade Commission is responsible for enforcing the federal law governing consumer reporting agencies, which means you can request your own copy and dispute entries that are wrong. Both are worth doing before you shop, because errors in these files are not rare: a claim recorded against the wrong address, a cause code that does not match what happened, a reported amount that reflects an initial reserve rather than what was actually paid.
A related point that saves people real money. At a large carrier, a recorded claim and a general coverage question are two different events, but the line between them is thinner than it sounds. If you call, describe a loss, give an address, and the system opens a file, that can be reported even if no money is ever paid. If you want to understand coverage without creating a record, ask your question in the abstract, about the policy language rather than about an event at your house, or ask your independent agent, who can read the form without opening anything.
The non-renewal question, answered honestly
Being dropped after one claim is rare at a large national carrier and is almost never a reaction to the claim alone. Non-renewal decisions at that scale are driven by book management: a carrier reducing exposure in a wildfire or coastal territory, or exiting a line of business, or tightening roof-age rules across a whole state. Households with claims get caught in those passes first, but the pass was coming either way.
Every state's insurance department sets notice requirements for non-renewal, usually with a specified number of days and a written reason. That letter is useful. It tells you whether you were caught in a territory action, in which case your claim history is not the obstacle you think it is when you shop, or whether the reason is specific to your property, in which case fixing the underlying condition (the roof, the dog, the unrepaired water damage) is what makes you insurable again.
Before you decide anything, pull your declarations page, get the estimate in writing, and ask your carrier for the two numbers that actually govern the outcome. The decision gets much smaller once the arithmetic is on paper in front of you.