Buying a House and Told You Need a Survey? Which Kind, and Who Decides
title:Buying a House and Told You Need a Survey? Which Kind, and Who Decidesauthor:Lionel Karstenspublished:2026-09-28section:Propertywords:1,343read:6 min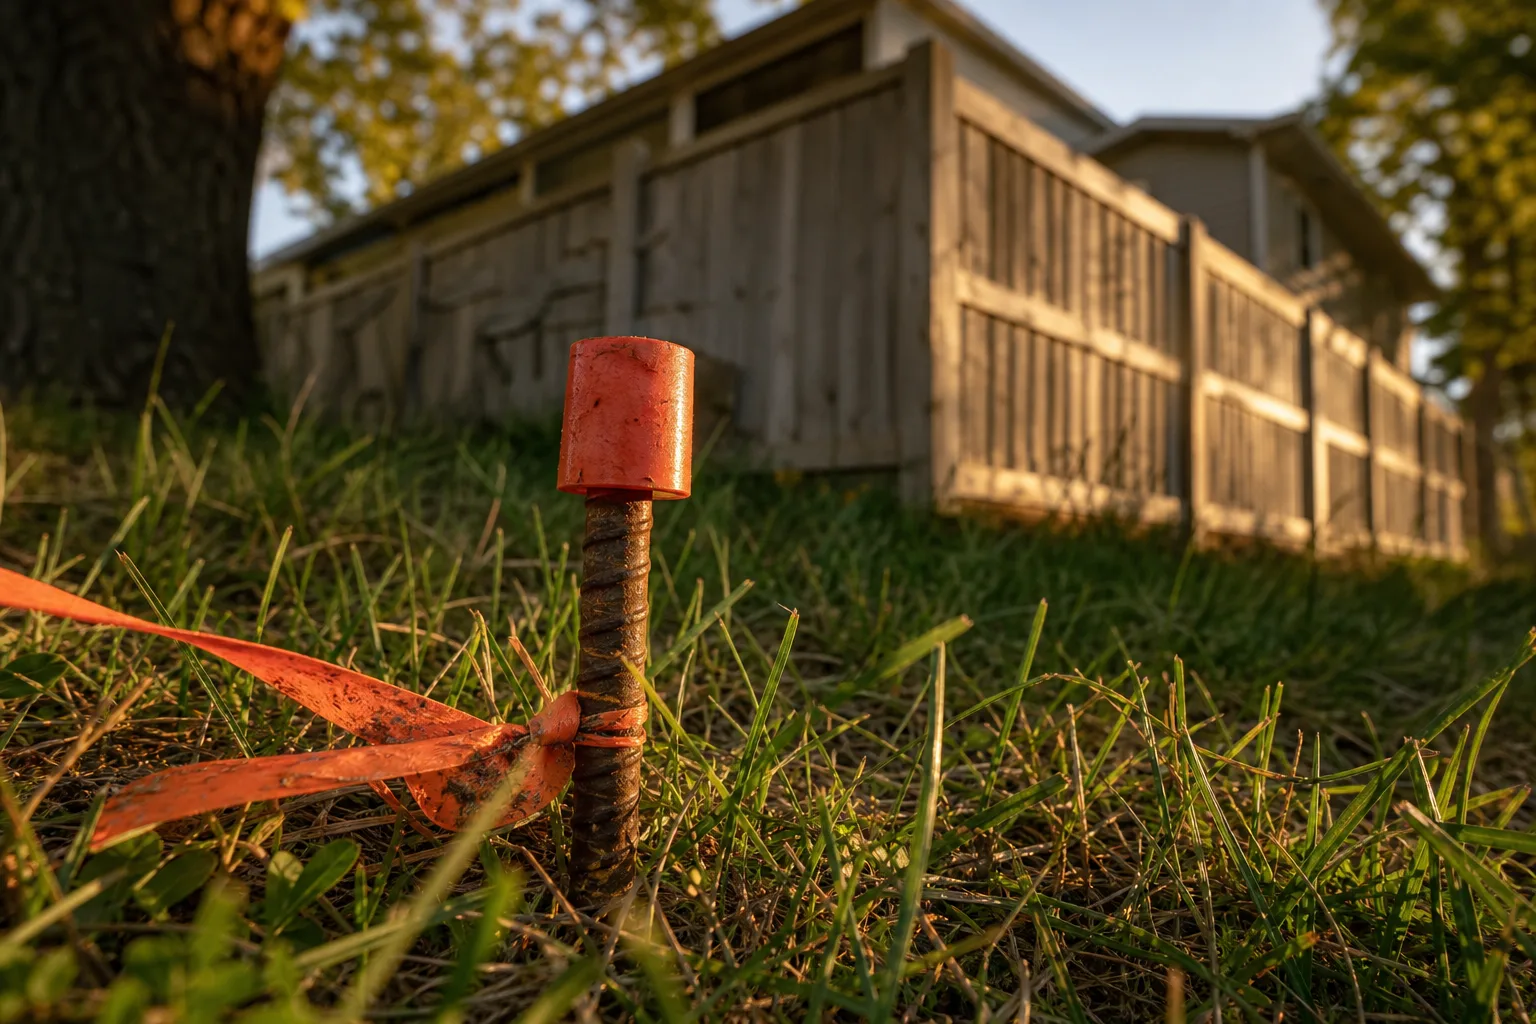
A boundary survey, an improvement location certificate and a mortgage inspection are not the same product, and the local rule usually picks for you.
The survey line on a closing disclosure is usually somewhere between a few hundred dollars and a few thousand, and most buyers approve it without knowing what arrives. What arrives varies enormously. One buyer gets a sealed drawing with iron pins physically driven at every corner. Another gets a one-page sketch stamped with a disclaimer saying it is not a boundary survey and should not be relied on to build a fence. Both were called "the survey" by the person who ordered it.
The difference is not the surveyor being lazy. It is that the product was defined by whoever asked for it, most often the title company or the lender, and they asked for the cheapest thing their underwriter accepts in that state. If you want the version that settles a fence line ten years from now, you have to ask for it by name and be willing to pay the gap.
What actually happens in the field, and what gets skipped
A full boundary survey starts in the records room, not the yard. The crew pulls the recorded subdivision plat, the deeds for your parcel and the adjoiners, any recorded easements, and prior surveys of nearby lots. That research is half the job and none of it is visible to you. Then someone goes out with GPS receivers running corrections off a network base, or a total station where tree canopy kills the satellite signal, and looks for physical evidence: existing iron rods, pipe, a chiseled cross in a curb, a monument the county set decades ago.
Found monuments outrank math. If an old pin sits eight inches off where the deed calculation lands, a competent surveyor documents the pin and holds it, because occupation and original monuments carry weight that a calculated point does not. What gets skipped on the cheap version is exactly this: nobody searches for the back corners in the brush, nobody sets new pins where the old ones are gone, and nobody drafts the found-versus-set distinction onto the map. You get a picture of the lot scaled from the recorded plat with the house sketched in.
On a real job you should see flagging tape at the corners when the crew leaves, and rebar with a plastic cap carrying the surveyor's license number. If nothing is in the ground, no one measured your corners.
The four products, and what each one is accepted for
These names are not interchangeable, and using the wrong one at the wrong moment is where money gets wasted.
| Product | What you get | Typically accepted for | Not good for |
|---|---|---|---|
| Boundary survey | Sealed map, corners monumented, easements plotted, legal description checked | Fences, additions, disputes, title exception deletion | Nothing, this is the full version |
| Improvement location certificate or mortgage inspection | Sketch showing house position relative to lines, no pins set, disclaimer on the face | Lender and title comfort at closing | Building anything near a line |
| ALTA/NSPS land title survey | Boundary work plus title commitment items, utilities, access, optional Table A items | Commercial purchases, some high-value residential | A routine tract home, it is overkill |
| Elevation certificate | Structure elevations tied to a vertical datum, flood zone data | Flood insurance rating, some permits | Anything to do with boundaries |
The elevation certificate is the one buyers most often confuse with a survey. It is produced by a surveyor and it says nothing about where your property ends. The Federal Emergency Management Agency is responsible for the flood mapping and the certificate form that insurers and floodplain administrators work from, and in a mapped flood zone the certificate can move an annual premium by an amount that dwarfs the survey fee. Order it as a separate line item, and order it early enough that the number is in hand before your rate lock expires.
Where the local rule decides for you
This is the part nobody explains at the closing table. The survey product that is normal in one state is unavailable or unacceptable in the next.
In Colorado, the standard closing document is an improvement location certificate. It is explicitly not a boundary survey, it says so on its face, and if you want corners in the ground you order an improvement survey plat instead, at a higher price. In parts of New England, the mortgage inspection plan plays the same role and carries the same limitation. In Texas, the common path is different again: rather than buying a new survey, the seller provides an existing survey plus a sworn affidavit confirming nothing has changed since it was made, and the title company decides whether to accept that combination and delete the survey exception from the policy. Iowa and a handful of other states have plat-filing requirements that mean certain survey work gets recorded with the county whether you like it or not, which is useful later because the next owner can find it.
Layered on top of state practice is the county and municipal layer. A city building department may require a current survey with a specific certification date before it issues a permit for a detached garage. A subdivision recorded with a homeowners association may impose setbacks tighter than zoning, enforced by an architectural committee that reads the plat more carefully than the city does. Coastal and lakefront parcels add a whole separate question about where the boundary actually sits when the water moves.
Ask two questions of your title officer, in writing: what survey product do you require to delete the survey exception, and will the local permit office accept that same product. When the answers differ, buy the stronger one once rather than the weak one twice.
The paperwork that makes it manageable
A survey is only as useful as the documents you hand the surveyor and the documents you keep afterward. The set worth assembling:
- The title commitment, Schedule B. Every recorded easement and restriction affecting the parcel is listed here. Send it to the surveyor before fieldwork. If they do not have it, the easements will not be plotted, and an easement you cannot see is the one that kills a pool plan.
- The legal description from the deed. Not the address. The surveyor checks whether the description closes mathematically and whether it matches the neighbors' descriptions.
- Prior surveys, including the seller's. Ask the seller during the inspection period. An older sealed survey is worth real money even if it needs updating.
- A written scope and deliverables list. Number of paper copies, a sealed PDF, whether corners will be monumented, whether the certification names you and your lender and your title company. Certifications are not transferable by default. A survey certified only to the seller's 2016 lender may be useless to you.
- The recorded plat and any HOA declaration. Setbacks, building envelopes, no-build strips.
Keep the sealed copy with the deed, not in a drawer with the appliance manuals. When a neighbor puts a post in, the person holding the dated, sealed drawing with monuments referenced on it is the person whose version of the line prevails without litigation.
Timing it inside the transaction
Survey work is weather-dependent and crew-dependent, and in a busy market the backlog in a given county can run weeks. Order during the inspection period, not after appraisal, because the survey is one of the few items that can surface a problem you would actually walk away over: a driveway encroaching from next door, a shed sitting across the line, an access easement nobody disclosed. Those findings are cheap to act on before closing and expensive afterward.
Budget for the stronger product on any parcel with acreage, an irregular shape, an old legal description written in metes and bounds, or any plan to build within ten feet of a line. On a platted tract lot where you intend to change nothing, the lender's standard product genuinely may be enough.
The buyers who end up satisfied are the ones who treated the survey as their document rather than the lender's errand, named the product they wanted, and got the corners marked while the crew was already on the street.